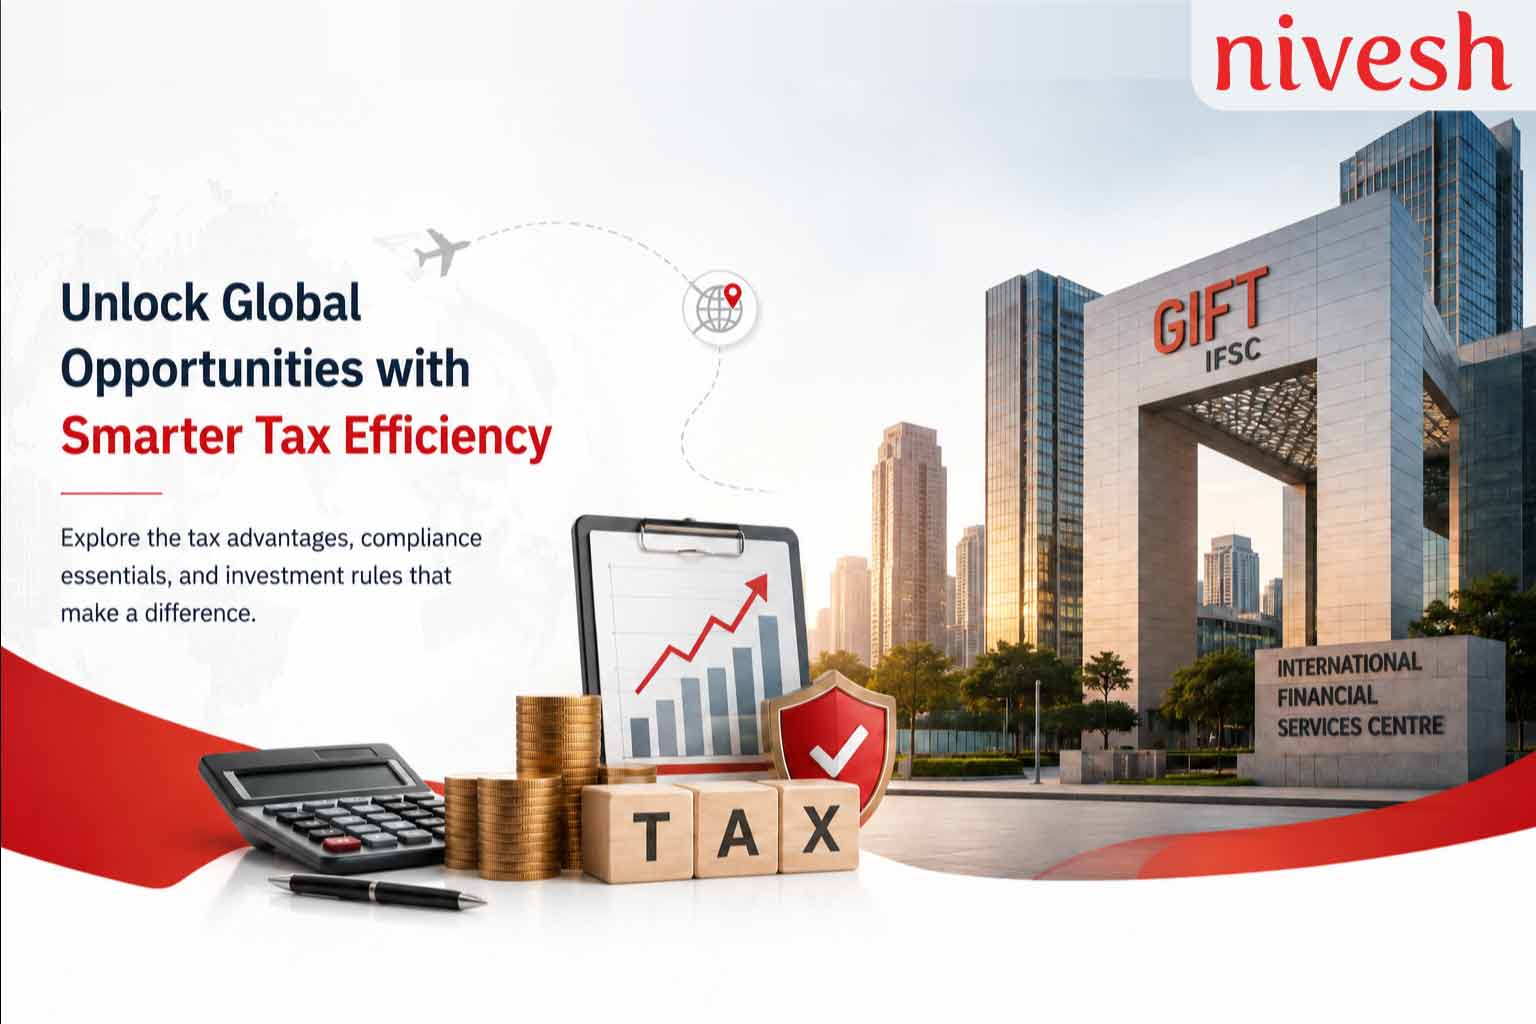
If you've been researching where to park your money for better returns and lower tax friction, chances are GIFT City has come up in conversation. It's rapidly becoming India's answer to global financial hubs like Singapore and Dubai, and a big part of that appeal comes down to GIFT City taxation. But how much of it is genuine advantage, and how much is oversimplified marketing? Let's break it down properly.
What Makes GIFT City Different
GIFT City (Gujarat International Finance Tec-City) is India's first International Financial Services Centre (IFSC), designed to let residents, NRIs, and global investors access international-style financial products without leaving the country's regulatory umbrella. The core pitch is simple: GIFT City tax benefits apply at both the fund/structure level and, in specific cases, the investor level, but the two shouldn't be confused.
Here's the important nuance most people miss: many exemptions apply to the fund structure operating within the IFSC, not automatically to every rupee an investor earns. Your personal tax liability still depends on your residency status, the nature of the income, and how the investment is structured.
Gift City Tax Benefits
Section 10(4D) Exemptions
Specified income earned by certain IFSC-domiciled funds is exempt from tax, subject to conditions. This lowers the effective cost of running a fund out of GIFT City, and that efficiency is typically passed on to end investors through better structuring and reduced fees.
No STT, CTT, or Stamp Duty
Unlike domestic Indian markets, trades executed within GIFT-IFSC are largely exempt from Securities Transaction Tax (STT), Commodities Transaction Tax (CTT), and stamp duty. If you're used to paying STT on every domestic equity trade, this is a real, quantifiable saving over time, though it doesn't mean your capital gains are automatically untaxed.
Tax Holiday for IFSC Entities
Entities operating from GIFT IFSC can claim a tax holiday, a 100% deduction on eligible business income for a defined number of consecutive years within a longer block period. This is one of the strongest incentives driving fund managers and financial institutions to set up shop in GIFT City rather than offshore jurisdictions.
No Capital Gains Tax for NRIs (Conditional)
For NRIs investing or trading through GIFT IFSC exchanges, long-term and short-term capital gains can be exempt or significantly reduced compared to domestic Indian markets, a major reason NRI investment interest in GIFT City has grown steadily.
No GST on Fund Management Charges
Investors don't pay GST on fund management charges (FMC), translating into an annual saving of roughly 18% on those charges alone, a benefit that compounds meaningfully over a multi-year holding period.
Non-PFIC Status
By completing regulatory filings (such as Form 8832 with US authorities), GIFT City funds can be classified as Non-PFIC. This matters specifically for US-connected investors, who would otherwise face onerous PFIC reporting and tax treatment on foreign fund holdings.
TCS: The Most Misunderstood Cost
A lot of hesitation around GIFT City investments comes from a single objection: "20% TCS is too expensive." Here's the reframe worth understanding: Tax Collected at Source (TCS) on outward remittances above the exemption threshold (currently ₹7 lakh for most LRS remittances) is not an additional tax. It's fully creditable against your final tax liability when you file your return. If your liability turns out lower than the TCS collected, the excess is refunded. In other words, TCS is a cash-flow timing issue, not a permanent cost, and spreading large remittances across financial years can further soften any near-term impact.
Avoiding Double Taxation: DTAA
For anyone with cross-border income touchpoints, the Double Taxation Avoidance Agreement (DTAA) between India and other countries is essential. It prevents the same income from being taxed twice, typically through an exemption method or a tax-credit method. To claim these benefits, you'll generally need a Tax Residency Certificate (TRC) and Form 10F, documentation that's non-negotiable if you want DTAA relief to actually apply.
GIFT City Investments: Resident vs NRI Rules

One of the most practical distinctions in GIFT City taxation is how resident Indians and NRIs are treated differently:
|
Parameter |
Resident Indian |
NRI |
|
Remittance route |
LRS (USD 250,000/year cap) |
No LRS cap — invests via foreign-sourced funds |
|
TCS applicability |
Applies above the exemption threshold |
Not applicable |
|
Tax on global income |
Taxed on worldwide income |
Taxed only on India-sourced income |
|
DTAA relevance |
Relevant when investing via foreign structures |
Highly relevant for India-sourced income |
For residents, every GIFT City investment is routed through the Liberalised Remittance Scheme (LRS), RBI's framework allowing individuals to remit up to USD 250,000 per financial year for permitted purposes, including overseas-style investment. This operates under the broader GIFT City regulations set out by FEMA (Foreign Exchange Management Act), which governs all cross-border capital flows.
NRIs, by contrast, aren't bound by the LRS cap since they invest using foreign-sourced funds, but their India-sourced income still needs careful DTAA planning.
GIFT City Compliance: What You Still Need to Report
Tax efficiency doesn't mean zero reporting. If you redeem holdings in a GIFT City product, applicable capital gains tax is assessed based on your holding period and structure type, and proceeds remitted back to your resident account go through standard banking documentation. Crucially, foreign assets and related income must still be disclosed in your Indian income tax return, typically under Schedule FA. Skipping this is one of the most common (and costly) compliance mistakes investors make.
Gifts, Estate Planning, and GIFT City
GIFT City also plays a role beyond direct investing. Gifts between specified relatives (parents, children, spouse) remain generally exempt from gift tax in India, while gifts to non-relatives above a specified threshold may be taxable in the recipient's hands. Since India abolished estate duty decades ago, the bigger complexity often lies abroad; assets held in foreign jurisdictions may still attract that country's estate or inheritance rules. Structuring global assets through GIFT City can simplify succession planning compared to holding assets directly across multiple foreign jurisdictions.
The Bottom Line
GIFT City's tax framework is genuinely attractive; tax holidays, STT/CTT exemptions, GST savings on fund charges, and simplified compliance for IFSC entities all add up to a compelling structure. But the smartest approach is to separate fund-level exemptions from your own investor-level obligations. Capital gains, TCS, DTAA documentation, and Schedule FA reporting don't disappear just because the fund itself is tax-efficient.
If you're evaluating GIFT City investments, whether as a resident using the LRS route or an NRI investing directly, the right move is to map out your specific residency status, remittance route, and reporting obligations before committing capital. Done right, GIFT City offers one of the most efficient ways to access global-style financial products from within India's regulatory system.